Food for thought - is collagen food for VAT purposes?
A reminder of the complexities of food for VAT purposes in the case of Minerva Research Labs Limited v HMRC [2026] UKFTT 1320 (TC)
29 Sep 2026
Minerva Research Labs Limited v HMRC [2026] UKFTT 1320 (TC)
Background
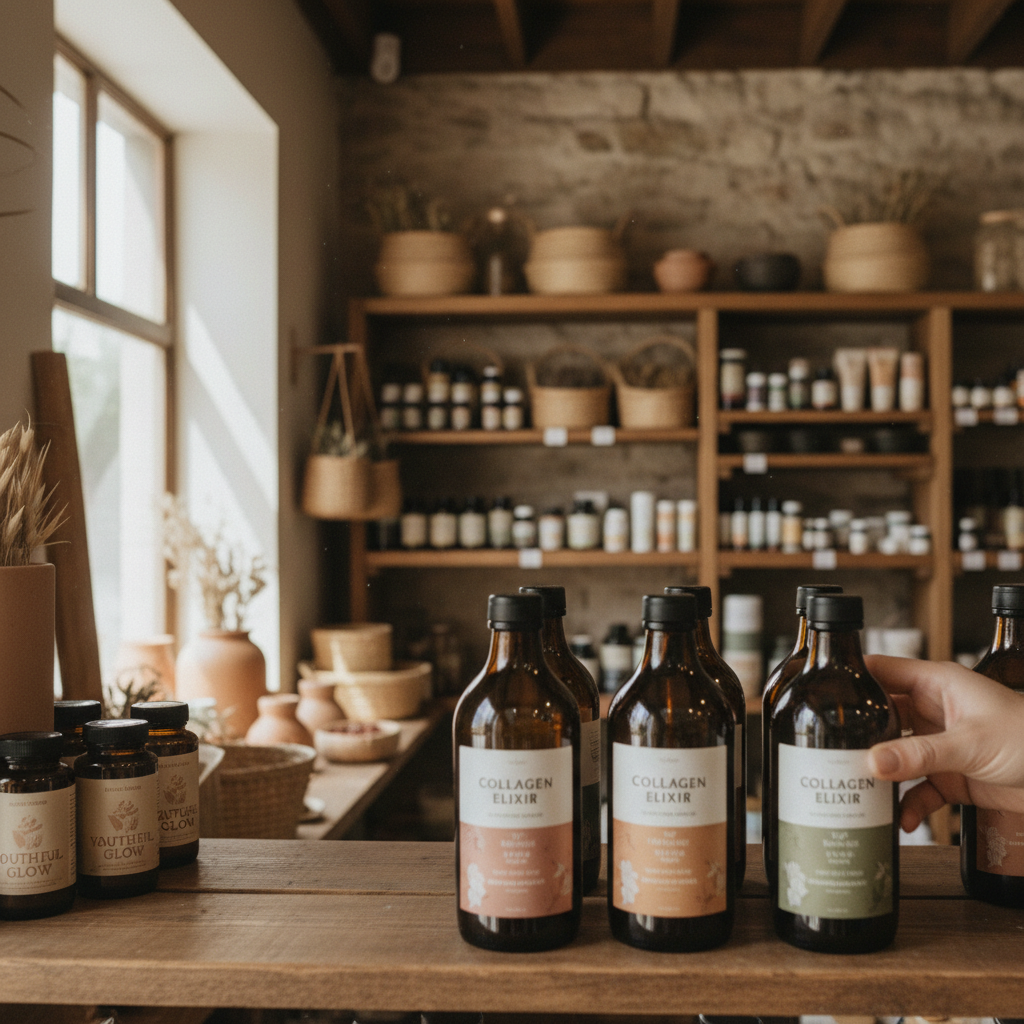
The company sells a range of collagen-based products. Mr Sanguinetti (the owner of Minerva) described them as a “perfect blend of nutritional ingredients to act as a building block for great skin, great hair, functional joints and muscles”.
The issue
The company believed the products should be classified as “food of a kind used for human consumption”, and subject to VAT at the zero-rate. It put in a claim for overdeclared output tax over a 4-year period (2018-2022) amounting to just over £3.6m.
What happened?
Both parties agreed the products are not beverages (which are liable to VAT at the standard rate). Beverages are consumed “to increase bodily liquid levels, to slake the thirst, to fortify or to give pleasure”, see Bioconcepts Ltd v C & E Comrs [1993] VAT Decision 11287.
The parties agreed a multi-factorial assessment was needed to determine VAT liability. Key points considered included:
- Why it was consumed (mainly anti-ageing, rather than nutritional benefits)
- How it was held out for sale (as “liquid beauty products”)
- How they were marketed (not as a meal or snack)
- Language used in marketing (“dose”, “treatment”)
- Labelling of the product (contained warnings and precautions you would not expect to see on food items)
Summary
The product was deemed not to be a zero-rated food item despite being palatable and nourishing. Marketing, labelling and the reason for people purchasing plays an important role in the VAT liability determination.
Another interesting addition to the library of case law on VAT liability of food items!